Available
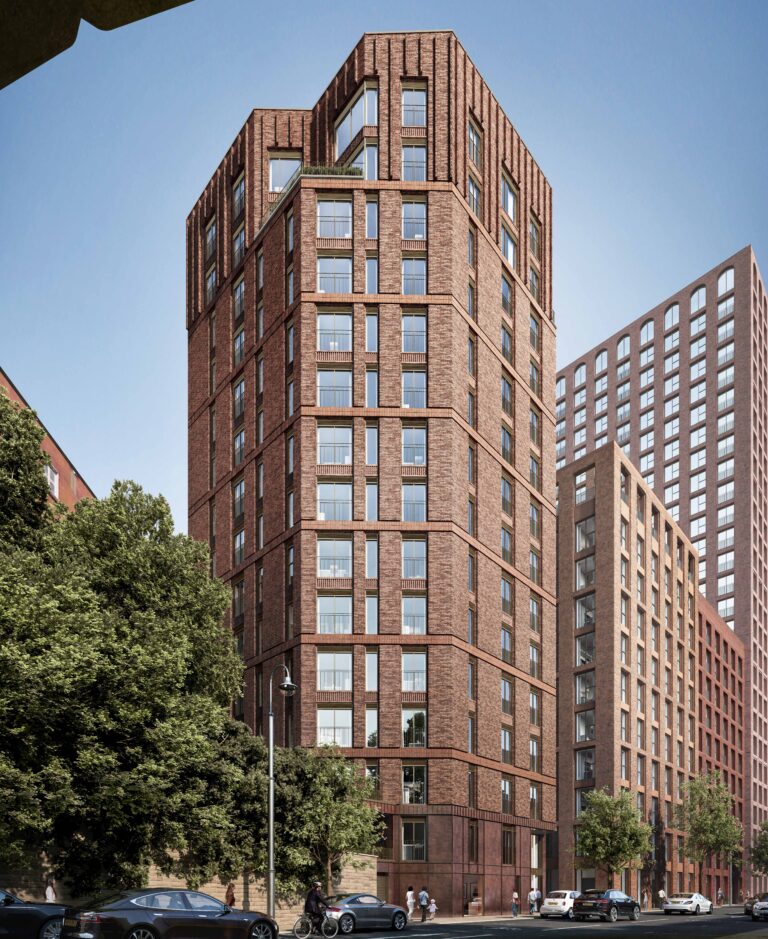
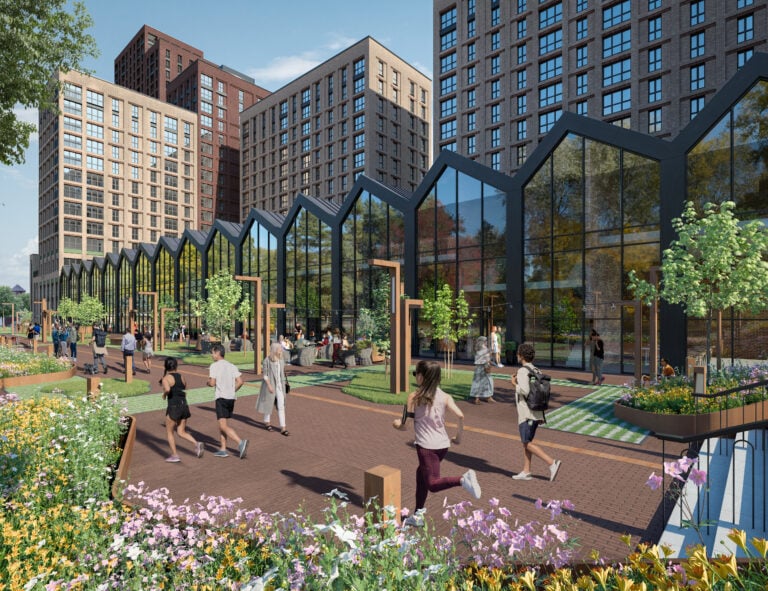
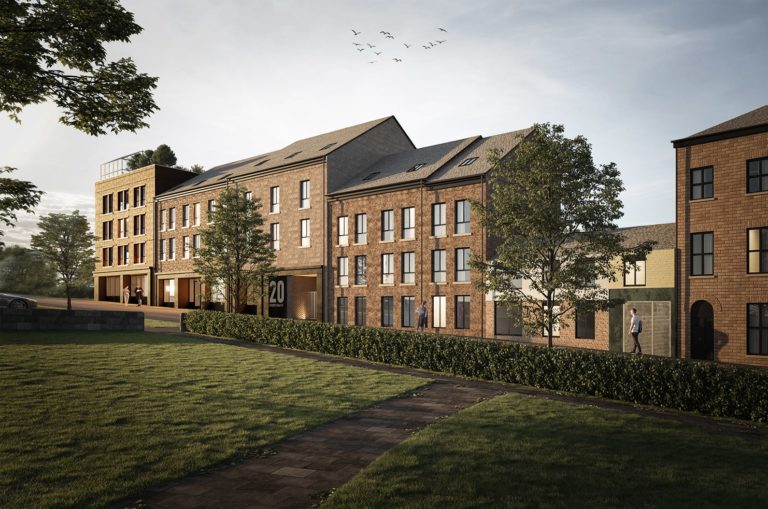
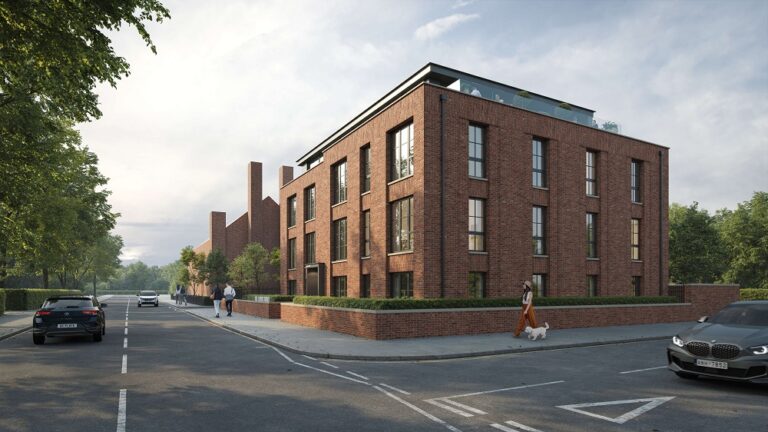
Peelers Yard
Manchester
A landmark piece of Manchester's history, reimagined as a residential development designed for long-term living and lasting investment performance.
Price
From £287,000


Manchester is one of the UK’s leading property investment markets, with billions of pounds of regeneration transforming the city and creating new homes, jobs and neighbourhoods. Its growing national importance has been underlined by the creation of No 10 North, establishing a permanent Downing Street presence in the city.
The city’s transformation has led to impressive capital and rental growth, with official figures showing property prices have risen by 73.4% over the past decade and average rents by 70.6%.
There follows an in-depth guide to Manchester property investment, including the current market, rental yields and buy-to-let opportunities, the best areas to invest and the factors driving future growth.
You can also explore our latest Manchester investment properties, speak to one of our property investment consultants or download our Manchester Property Investment Guide.
								Array
(
    [ID] => 6100285
    [id] => 6100285
    [title] => Victoria Park ext cgi back
    [filename] => Victoria-Park-ext-cgi-back-scaled.jpg
    [filesize] => 1221746
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-scaled.jpg
    [link] => https://www.buyassociationgroup.com/en-gb/daisy-bank-park/victoria-park-ext-cgi-back-2/
    [alt] => Victoria Park Manchester Back
    [author] => 4200
    [description] => Manchester Victoria Park ext cgi back
    [caption] => Back of Victoria Park Manchester
    [name] => victoria-park-ext-cgi-back-2
    [status] => inherit
    [uploaded_to] => 6100414
    [date] => 2024-04-08 15:33:08
    [modified] => 2025-11-20 10:47:56
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 2560
    [height] => 1440
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-150x150.jpg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-300x169.jpg
            [medium-width] => 300
            [medium-height] => 169
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-768x432.jpg
            [medium_large-width] => 768
            [medium_large-height] => 432
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-1024x576.jpg
            [large-width] => 1024
            [large-height] => 576
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-1536x864.jpg
            [1536x1536-width] => 1536
            [1536x1536-height] => 864
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-2048x1152.jpg
            [2048x2048-width] => 2048
            [2048x2048-height] => 1152
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-125x125.jpg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-600x400.jpg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-500x300.jpg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/04/Victoria-Park-ext-cgi-back-750x350.jpg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)

Manchester has changed significantly over the past decade, with an estimated £8–10bn invested in regeneration as the city’s population and economy have grown. Over the same period, average property prices have risen from £144,935 to £251,250, and average monthly rents have increased from around £796 to £1,358.
| Investment metric | Manchester | Source/date |
|---|---|---|
| Average property price | £251,250 | HM Land Registry, June 2026 |
| Annual house price growth | 2.9% | HM Land Registry, June 2026 |
| 10-year house price growth | 73.4% | HM Land Registry, June 2026 |
| Average monthly rent | £1,358 | ONS, June 2026 |
| Annual rental growth | 3.5% | ONS, June 2026 |
| 10-year rental growth | 70.6% | ONS, June 2026 |
| Average gross rental yield | 6.5% | Calculated from HM Land Registry and ONS figures, June 2026 |
| Population | 645,097 | Manchester City Council, mid-2025 estimate |
| Student population | 125,000 | Greater Manchester Civic Universities Agreement, 2026 |
| Population growth | Around 42% over 20 years | Manchester City Council, 2005–2025 |
| Job growth | 19.7% over the past decade | Centre for Cities, 2026 |
| Knowledge-intensive business services jobs | 244,000 | Centre for Cities / Manchester City Council, 2026 |
| Planned investment | £10bn investment ambition over the next decade | Greater Manchester Combined Authority, Greater Manchester Growth Plan, 2026 |
								Array
(
    [ID] => 6090626
    [id] => 6090626
    [title] => An aerial view of Manchester build-to-rent properties
    [filename] => manchester-aerial-768x576-1.jpeg
    [filesize] => 87256
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1.jpeg
    [link] => https://www.buyassociationgroup.com/en-gb/investments/manchester-aerial-768x576/
    [alt] => An aerial view of Manchester build-to-rent properties property investment
    [author] => 4195
    [description] =>
    [caption] =>
    [name] => manchester-aerial-768x576
    [status] => inherit
    [uploaded_to] => 6
    [date] => 2022-11-18 11:39:58
    [modified] => 2025-07-18 14:20:47
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 768
    [height] => 576
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1-150x150.jpeg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1-300x225.jpeg
            [medium-width] => 300
            [medium-height] => 225
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1.jpeg
            [medium_large-width] => 768
            [medium_large-height] => 576
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1.jpeg
            [large-width] => 768
            [large-height] => 576
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1.jpeg
            [1536x1536-width] => 768
            [1536x1536-height] => 576
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1.jpeg
            [2048x2048-width] => 768
            [2048x2048-height] => 576
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1-125x125.jpeg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1-600x400.jpeg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1-500x300.jpeg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/manchester-aerial-768x576-1-750x350.jpeg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)
Manchester has one of the UK’s strongest property markets, with its combination of high rental demand, competitive yields, long-term capital growth, a growing population and extensive regeneration. Research by The Property Buying Company found it was the most sought-after city, with 23% of buy-to-let investors targeting it, compared to 18% for London.
Manchester’s population has grown by around 42% over the past 20 years to more than 645,000. Around 40% of the city’s homes are privately rented, with younger people making up a particularly large part of the population and rental market.
Greater Manchester also has more than 125,000 university students. Around 40% of graduates remain in the city region after completing their studies, helping to replenish its population of young professionals and supporting demand beyond the student market.
Housing supply has struggled to keep pace with this level of growth. As a result, average Manchester rents have risen by around 44% over the past five years, and the average rental property took 21 days to let during the second quarter of 2026, with 40% finding a tenant within two weeks.
Sources: Manchester City Council, 2025/26; Greater Manchester Civic Universities, 2026; ONS, June 2026.
Manchester’s average gross rental yield is currently around 6.5%, but returns vary considerably by property type and location.
Higher returns are available from flats, HMOs and some central locations. However, the headline figure is only part of the calculation, as service charges, maintenance, licensing and other operating costs can all affect the income an investor receives.
For a more detailed breakdown, see What Rental Yields Can Investors Expect in Manchester? (Internal link to Section 10)
Sources: HM Land Registry and ONS, June 2026. Yields calculated from average property prices and rents.
Manchester has recorded substantial long-term capital growth. Average property prices have risen by 73.4% over the past decade and were 2.9% higher year-on-year in June 2026, compared with 1.8% in the rest of the UK.
And there is potential for further growth, as Manchester’s population and economy expand and investment in regeneration and infrastructure creates new places to live and work. However, the balance between housing supply and demand will vary between individual postcodes and developments.
Savills forecasts average North West property price growth of 27.6% between 2026 and 2030, compared to 22.2% for the UK and 13.6% for London.
Sources: HM Land Registry, June 2026; Savills Research, 2025/26; Manchester City Council, 2026.
Manchester’s expanding economy is another major driver of housing demand. Jobs in Manchester and the wider city region have increased by 19.7% over the past decade, which is considerably above the national average (13.9%).
Manchester now has around 244,000 knowledge-intensive business-services jobs, second only to London among major UK cities. Its universities and established technology, digital and creative sectors are being joined by growing financial, professional and government employment.
Global financial services company BNY is relocating more than 2,000 staff to the 200,000 sq ft 4 Angel Square at NOMA, and UK semiconductor and computing technology company Arm has more than doubled its Manchester office footprint, moving from a 29,000 sq ft office to around 70,000 sq ft at St Michael’s. In addition, the Manchester Digital Campus is now under construction in Ancoats and is expected to accommodate around 8,800 government staff when it opens its doors.
Sources: Manchester City Council, 2025/26; BuyAssociation, 2026.
Manchester has an extensive pipeline of regeneration, housing and infrastructure investment that will change both the city centre and the wider city region over the coming years.
The city’s new Local Plan will guide development for the next 15 years, with a target to deliver at least 36,000 new homes by 2032. Major projects include Victoria North, Mayfield, Ancoats, the Manchester Digital Campus, Atom Valley and the proposed regeneration around Old Trafford.
Longer-term plans around Manchester Piccadilly could create thousands more homes and jobs, while Northern Powerhouse Rail is intended to improve connections between Manchester, Liverpool, Leeds and other northern cities. There are also proposals to restore a high-speed rail connection between Birmingham and Manchester.
For investors, the potential impact of regeneration depends on the individual location. New employment, transport links and amenities can increase the appeal of an area, but the amount and type of new housing being delivered also needs to be considered.
Sources: Manchester City Council; Greater Manchester Combined Authority; UK Government; BuyAssociation, 2025/26.
								Array
(
    [ID] => 6099946
    [id] => 6099946
    [title] => Manchester (2)
    [filename] => Manchester-2.jpg
    [filesize] => 381522
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2.jpg
    [link] => https://www.buyassociationgroup.com/en-gb/news/7am-cut-2/manchester-2-2/
    [alt] =>
    [author] => 4212
    [description] =>
    [caption] =>
    [name] => manchester-2-2
    [status] => inherit
    [uploaded_to] => 6099945
    [date] => 2024-03-15 16:00:08
    [modified] => 2024-03-15 16:00:08
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 1500
    [height] => 942
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-150x150.jpg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-300x188.jpg
            [medium-width] => 300
            [medium-height] => 188
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-768x482.jpg
            [medium_large-width] => 768
            [medium_large-height] => 482
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-1024x643.jpg
            [large-width] => 1024
            [large-height] => 643
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2.jpg
            [1536x1536-width] => 1500
            [1536x1536-height] => 942
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2.jpg
            [2048x2048-width] => 1500
            [2048x2048-height] => 942
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-125x125.jpg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-600x400.jpg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-500x300.jpg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2024/03/Manchester-2-750x350.jpg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)

Manchester has performed relatively strongly during a challenging year for the wider UK property market, with property prices and rents still rising and rental demand holding up well.
Manchester property prices were 2.9% higher year-on-year in June 2026, compared with 1.8% across the UK, with prices in London down 2.5%.
There are signs that demand there is holding up better, too. In August 2026, 33.1% of homes for sale in Greater Manchester had undergone an asking-price reduction, compared with 40.6% nationally, 42% in London and 43.4% in the South East.
Average Manchester rents reached £1,358 a month in June 2026, 3.5% higher than a year earlier. During the second quarter, the average Manchester rental property took 21 days to let, down from 24 days a year earlier, with 40% finding a tenant within two weeks. Over the same period, national rental enquiries per available property fell by almost 10%.
Borrowing costs have been volatile during 2026. Moneyfacts data shows the average five-year fixed buy-to-let mortgage rate rose from 5.05% at the beginning of March to 5.75% in April. Rates have since fallen back, although at 75% LTV the average five-year fixed rate was still 5.66% at the beginning of August (rates are considerably lower for those with larger deposits).
Higher mortgage rates increase financing costs and can reduce the returns available to leveraged investors, making the purchase price, achievable rent and size of the deposit particularly important.
Over 7,800 homes are currently under construction in Manchester, with a further 20,000 either approved or progressing through the planning system.
The impact of this new supply will vary considerably between locations. A large concentration of similar properties in one area, though, can increase competition for tenants and buyers. Investors therefore need to consider the scale and type of development planned locally alongside existing and future demand when assessing an individual area or development.
BuyAssociation offers investment opportunities ranging from city-centre apartments and off-plan developments to houses and HMOs at various stages of construction.
There is also a strong pipeline of future opportunities, supported by around £10bn of further regeneration and development planned in Manchester.
Manchester is performing relatively strongly in 2026, but property prices and rents can fall as well as rise. Finance costs can also increase, and any further changes to property taxation or regulation could affect costs and potential returns.
Sources: HM Land Registry and ONS, June 2026; Rentaroof, Q2 2026; Lyons Bowe Solicitors/Zoopla listings analysis, August 2026; The Property Buying Company, June 2026; Manchester City Council, 2026; BuyAssociation, 2025/26.
								Array
(
    [ID] => 6094323
    [id] => 6094323
    [title] => Aerial view of Manchester city in UK
    [filename] => Manchester-city-view-high-quality.jpg
    [filesize] => 3668191
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality.jpg
    [link] => https://www.buyassociationgroup.com/en-gb/news/manchester-property-b/aerial-view-of-manchester-city-in-uk/
    [alt] => Manchester property city view rental yields property investors rental demand north west
    [author] => 1069
    [description] =>
    [caption] => Aerial view of Manchester city in UK
    [name] => aerial-view-of-manchester-city-in-uk
    [status] => inherit
    [uploaded_to] => 6094304
    [date] => 2023-06-09 10:31:58
    [modified] => 2024-10-07 20:17:51
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 2000
    [height] => 1498
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-150x150.jpg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-300x225.jpg
            [medium-width] => 300
            [medium-height] => 225
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-768x575.jpg
            [medium_large-width] => 768
            [medium_large-height] => 575
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-1024x767.jpg
            [large-width] => 1024
            [large-height] => 767
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-1536x1150.jpg
            [1536x1536-width] => 1536
            [1536x1536-height] => 1150
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality.jpg
            [2048x2048-width] => 2000
            [2048x2048-height] => 1498
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-125x125.jpg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-600x400.jpg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-500x300.jpg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/06/Manchester-city-view-high-quality-750x350.jpg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)
One of the main attractions of buy-to-let in Manchester is its large private rented sector. Around 100,000 homes are privately rented, accounting for approximately 40% of Manchester’s housing stock, creating a sizeable market that serves a broad range of tenants.
Young adults make up a large proportion of Manchester’s rental market. More than 162,000 residents were aged between 20 and 34 at the 2021 Census, including graduates and working professionals.
Students are another important tenant group. Greater Manchester has more than 125,000 university students, and research for Manchester City Council found that 87% of students were living in privately rented accommodation.
The third core group is made up of couples and families, who tend to make up more of the market away from the city centre.
Manchester’s rapidly growing population is exerting increasing pressure on its housing stock, helping to support long-term rental demand. The city’s population has increased by around 42% over the past 20 years.
This has been accompanied by substantial rental growth. Average Manchester rents have risen by around 44% over the past five years, from approximately £940 a month in 2021 to £1,358 in June 2026.
Manchester has a diverse rental market, with investment properties ranging from modern apartments and traditional terraced houses to larger family homes.
Apartments range from studios and one-bedroom properties to larger two and three-bedroom homes and penthouses, with much of Manchester’s newer residential development concentrated in this part of the market. There are also plenty of terraced, semi-detached and detached houses.
HMOs are a growing part of Manchester’s rental market. A house in multiple occupation is rented \by three or more people from two or more households who share facilities such as a kitchen or bathroom.
City-centre apartments tend to attract students, graduates and young professionals looking for easy access to jobs, universities, transport links, shops, restaurants and entertainment.
Council research found that students were around twice as likely to live in flats or maisonettes as Manchester residents generally, with increasing numbers of second and third-year students renting in the mainstream private rented sector.
Properties further from the centre tend to appeal more to families and tenants looking for additional space, access to schools, green space and local amenities. Good transport links remain important, particularly for people commuting into Manchester for work.
Yields vary considerably according to property type. Flats and maisonettes currently offer the highest average gross yields among conventional property types, at around 7.0%, followed by terraced homes at 6.6%. Average yields are lower for semi-detached properties at 5.4% and detached houses at 4.7%, while specialist investments such as HMOs can produce yields of 10% or more. Location has an impact too, with average gross yields varying by around 1.3 percentage points between the highest and lowest-yielding areas.
Gross yield is only part of the calculation. City-centre apartments may have service charges and ground rent where applicable, whereas houses have different maintenance costs. HMOs have additional licensing and operating costs that need to be taken into account when comparing potential returns.
Management requirements vary according to the type of property. A conventional apartment or house let under a single tenancy will generally require less day-to-day management than an HMO, where landlords have additional licensing, safety and management responsibilities.
Landlords also need to account for maintenance, tenant management and void periods, as well as keeping up with regulatory requirements. The Renters’ Rights Act has brought significant changes to the way rental properties are let and managed.
BuyAssociation can connect buyers with independent lettings management services for those looking for a more hands-off investment.
								Array
(
    [ID] => 6095572
    [id] => 6095572
    [title] => Railway station concourse and information boards
    [filename] => Manchester-Piccadilly-station.jpg
    [filesize] => 2108327
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station.jpg
    [link] => https://www.buyassociationgroup.com/en-gb/news/manchester-stations/railway-station-concourse-and-information-boards/
    [alt] => Manchester Piccadilly station
    [author] => 1069
    [description] =>
    [caption] => Manchester, UK - May 4, 2011: Manchester Piccadilly railway station concourse. Piccadilly is the busiest railway station in the North of England and the third busiest in the United Kingdom.
    [name] => railway-station-concourse-and-information-boards
    [status] => inherit
    [uploaded_to] => 6095566
    [date] => 2023-08-31 11:19:44
    [modified] => 2023-08-31 11:20:14
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 2121
    [height] => 1414
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-150x150.jpg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-300x200.jpg
            [medium-width] => 300
            [medium-height] => 200
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-768x512.jpg
            [medium_large-width] => 768
            [medium_large-height] => 512
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-1024x683.jpg
            [large-width] => 1024
            [large-height] => 683
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-1536x1024.jpg
            [1536x1536-width] => 1536
            [1536x1536-height] => 1024
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-2048x1365.jpg
            [2048x2048-width] => 2048
            [2048x2048-height] => 1365
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-125x125.jpg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-600x400.jpg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-500x300.jpg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2023/08/Manchester-Piccadilly-station-750x350.jpg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)

|
Investment profile |
Manchester City Centre (M1) |
|---|---|
| Average sold price | £236,462 |
| Average asking rent | £1,476 pcm |
| Gross rental yield | 6.7% |
| 5-year capital growth | -14% |
| Property stock | Mainly apartments |
| Tenant profile | Young professionals, graduates and students |
| Key strengths | Employment, rental demand, transport, universities and regeneration |
Manchester city centre is the commercial and employment heart of the city, with a large concentration of offices, universities, shops and leisure facilities. Its population is a mixture of young professionals, graduates and students who want to live close to work and study.
It is a predominantly apartment-led rental market. Rents rose 10.4% over the year to Q2 2026, with the centre accounting for more rental properties than any other Manchester district in recent research. Average asking rents in M1 are currently £1,476 a month, with gross rental yields of 6.7%. Five-year capital growth has been weaker at -14%.
Its central position means it has excellent transport links, with Piccadilly and Victoria providing regional and national rail services and the Metrolink network connecting the centre with much of Greater Manchester.
The area’s development activity is extensive, with major schemes adding new homes, offices and amenities. In the longer term, plans for Manchester Piccadilly could deliver thousands of new homes and jobs.
								Array
(
    [ID] => 6106538
    [id] => 6106538
    [title] => buyassociation city index
    [filename] => Ancoats-House-balcony-small.png
    [filesize] => 1215709
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small.png
    [link] => https://www.buyassociationgroup.com/en-gb/property/buy-to-let-mortgages-explained-everything-you-need-to-know/ancoats-house-balcony-small-2/
    [alt] => buyassociation city index
    [author] => 4200
    [description] =>
    [caption] =>
    [name] => ancoats-house-balcony-small-2
    [status] => inherit
    [uploaded_to] => 6108349
    [date] => 2025-10-15 13:06:19
    [modified] => 2026-10-16 14:21:46
    [menu_order] => 0
    [mime_type] => image/png
    [type] => image
    [subtype] => png
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 1000
    [height] => 533
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-150x150.png
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-400x213.png
            [medium-width] => 400
            [medium-height] => 213
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-768x409.png
            [medium_large-width] => 768
            [medium_large-height] => 409
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small.png
            [large-width] => 1000
            [large-height] => 533
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small.png
            [1536x1536-width] => 1000
            [1536x1536-height] => 533
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small.png
            [2048x2048-width] => 1000
            [2048x2048-height] => 533
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-125x125.png
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-600x400.png
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-500x300.png
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/10/Ancoats-House-balcony-small-750x350.png
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)
| Investment profile | Ancoats and New Islington (M4) |
|---|---|
| Average sold price | £246,203 |
| Average asking rent | £1,384 pcm |
| Gross rental yield | 6.8% |
| 5-year capital growth | -8% |
| Property stock | Mainly apartments |
| Tenant profile | Mainly young professionals, couples, and sharers |
| Key strengths | City-centre location, transport, rental demand, regeneration, and employment |
Ancoats and New Islington are immediately to the east of Manchester city centre, next to the Northern Quarter. Decades of regeneration have turned the former industrial district into a largely residential area that is fast becoming an established part of the city centre.
Its convenient location drives demand, particularly from young professionals working in and around central Manchester. Piccadilly and the Northern Quarter are within walking distance, and New Islington has its own Metrolink stop. Current rental data shows Ancoats properties taking an average of just 12 days to let in Q2 2026, one of the fastest rates in Manchester.
Like the city centre, the market is dominated by apartments. Average asking rents are £1,384 a month, with gross rental yields of 6.8%. Capital growth has been weaker, though, with prices down 8% over five years.
There is more regeneration planned for the area. Manchester City Council is proposing another 1,500 homes, alongside new commercial space and improvements to transport and public areas.
Manchester Digital Campus should provide a further boost, with around 8,800 government staff expected to work at the 900,000 sq ft Ancoats campus, including No 10 North when it moves from its temporary base at Heron House in the city centre.
								Array
(
    [ID] => 6090239
    [id] => 6090239
    [title] => A large residential building in Salford, Manchester
    [filename] => salford-1024x683-1.jpeg
    [filesize] => 135089
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1.jpeg
    [link] => https://www.buyassociationgroup.com/en-gb/investments/salford-1024x683/
    [alt] => A large residential building in Salford, Manchester
    [author] => 4195
    [description] =>
    [caption] =>
    [name] => salford-1024x683
    [status] => inherit
    [uploaded_to] => 6
    [date] => 2022-11-15 15:46:29
    [modified] => 2023-11-30 16:28:26
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 1024
    [height] => 683
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-150x150.jpeg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-300x200.jpeg
            [medium-width] => 300
            [medium-height] => 200
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-768x512.jpeg
            [medium_large-width] => 768
            [medium_large-height] => 512
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1.jpeg
            [large-width] => 1024
            [large-height] => 683
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1.jpeg
            [1536x1536-width] => 1024
            [1536x1536-height] => 683
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1.jpeg
            [2048x2048-width] => 1024
            [2048x2048-height] => 683
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-125x125.jpeg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-600x400.jpeg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-500x300.jpeg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2022/11/salford-1024x683-1-750x350.jpeg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)

| Investment profile | Salford Quays (M50) |
|---|---|
| Average sold price | £193,202 |
| Average asking rent | £1,207 pcm |
| Gross rental yield | 6.7% |
| 5-year capital growth | -3% |
| Property stock | Mainly modern apartments |
| Tenant profile | Mainly professionals and couples |
| Key strengths | MediaCity, employment, transport, rental demand, and regeneration |
Salford Quays is based around the former Manchester Docks and around two miles west of Manchester city centre. Decades of regeneration have created a major new residential and employment district, with MediaCity at its centre.
Local employment opportunities are a key driver of housing demand. MediaCity is home to the BBC and ITV alongside a large cluster of media, digital and technology businesses. Local agents report particularly strong demand from professionals working in these sectors.
The property market is dominated by modern apartments, in what is a high-density residential area. Average asking rents in M50 are £1,207 a month, with gross rental yields of 6.7%. Capital growth has been more subdued, at -3% over five years.
It has good transport links, with several Metrolink stops providing direct connections with Manchester city centre and other parts of Greater Manchester.
There is further expansion planned at MediaCity, which will add more homes, commercial space and amenities.
								Array
(
    [ID] => 6104236
    [id] => 6104236
    [title] => Victoria Mills, Manchester
    [filename] => Reddish-Stockport.jpg
    [filesize] => 1206363
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport.jpg
    [link] => https://www.buyassociationgroup.com/en-gb/victoria-mills-manchester/
    [alt] => Reddish Stockport
    [author] => 1069
    [description] =>
    [caption] => Imge of Victoria Mills Manchester on a spring landscape
    [name] => victoria-mills-manchester
    [status] => inherit
    [uploaded_to] => 0
    [date] => 2025-02-07 14:24:13
    [modified] => 2025-02-07 14:24:46
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 1254
    [height] => 836
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-150x150.jpg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-400x267.jpg
            [medium-width] => 400
            [medium-height] => 267
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-768x512.jpg
            [medium_large-width] => 768
            [medium_large-height] => 512
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-1024x683.jpg
            [large-width] => 1024
            [large-height] => 683
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport.jpg
            [1536x1536-width] => 1254
            [1536x1536-height] => 836
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport.jpg
            [2048x2048-width] => 1254
            [2048x2048-height] => 836
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-125x125.jpg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-600x400.jpg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-500x300.jpg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2025/02/Reddish-Stockport-750x350.jpg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)

|
Investment profile |
Stockport town centre (SK1) |
|---|---|
| Average sold price | £211,597 |
| Average asking rent | £955 pcm |
| Gross rental yield | 5.5% |
| 5-year capital growth | +38% |
| Property stock | Apartments, terraces and houses |
| Tenant profile | Professionals, commuters, couples and families |
| Key strengths | Capital growth, connectivity, regeneration and housing choice |
Stockport is around seven miles south-east of Manchester. Its housing market is much broader than central Manchester and ranges from town-centre apartments and Victorian terraces to larger suburban family homes.
Its fast rail links are a major driver of demand, with journeys from Stockport to Manchester Piccadilly taking under ten minutes. It has a broad-based rental market, including professionals and commuters, alongside couples and families who want more space. Properties close to Stockport station are particularly sought after.
Average asking rents in SK1 are currently £955 a month, with gross rental yields of 5.5%. Capital growth has been an impressive 38% over five years.
The town centre is currently undergoing a major transformation, with more than £1bn of regeneration investment. New housing is turning parts of the centre that were traditionally commercial into residential neighbourhoods, alongside improvements to transport, public spaces and amenities.
And there is more planned. Stockport Council’s Town Centre East Strategic Regeneration Framework proposes another 4,000 homes, potentially taking the total number of new homes delivered or planned in the town centre to around 8,000.
Manchester city centre and Greater Manchester offer different investment characteristics, from purchase prices and rental yields to housing stock, tenant markets and capital growth.
Manchester city centre is predominantly an apartment market, whereas Greater Manchester has a broader mix of apartments, terraces, semi-detached and detached houses.
Purchase prices vary significantly by location and property type. Moving further from the centre does not necessarily mean buying more cheaply, particularly in established areas such as Sale and Altrincham, where family houses can cost more than central Manchester apartments.
Rental demand is strong in both markets, but the tenant mix differs. The city centre has a particularly high concentration of young professionals, graduates and students, whereas Greater Manchester has a broader tenant base that includes more commuters, couples and families.
As a result, tenant turnover can be markedly different. Younger renters, students and sharers tend to be more mobile, whereas families and older tenants are more likely to stay for longer. The English Housing Survey found that 48% of private renters with children had been in their home for three to nine years, compared to just 35% of those without children.
Rental yields tend to be higher in Manchester city centre than in many parts of Greater Manchester. Apartments in particular currently average around 7.0% across Manchester, compared with 6.6% for terraced homes, 5.4% for semi-detached properties and 4.7% for detached houses.
However, apartments typically come with service charges and other leasehold costs that reduce net rental income. With houses, the owner or their agent is generally responsible for maintaining the building and any outside space, giving them greater control over ongoing costs. The difference between gross and net returns therefore needs to be carefully considered when comparing the two markets.
Manchester city centre has excellent public transport, including the Metrolink network, extensive bus services and major rail stations at Piccadilly and Victoria. Many tenants can also live within walking distance of their workplace, universities, shops and other amenities.
Transport needs more careful consideration in Greater Manchester, particularly for tenants commuting into the city. Locations close to fast rail or Metrolink connections can therefore have an advantage over less well-connected areas.
Although both Manchester city centre and Greater Manchester are benefiting from substantial regeneration and investment, the recent capital growth picture is very different. Some central Manchester apartment markets have recorded relatively weak five-year price growth, with prices down 14% in M1 and 8% in M4, whereas other parts of Greater Manchester have performed considerably more strongly.
Stockport town centre, for example, has recorded five-year growth of 38%. One of the reasons for the weaker property price growth in central Manchester is the very different property mix, with apartments dominating the central market compared with the much broader mix of housing found elsewhere.
Past performance, though, is no guarantee of future growth, and the differing performances show why investors need to look beyond Manchester-wide averages when considering the potential for capital appreciation in individual locations.
Neither market is necessarily better. Manchester city centre may suit investors prioritising rental income, although higher tenant turnover can mean more management and reletting.
Greater Manchester offers a wider choice of properties and locations and may suit investors looking for longer tenancies or stronger capital growth potential.
Ultimately, the choice depends on the investor’s budget, goals and priorities.
Manchester offers a wide choice of investment property, from conventional buy-to-let apartments and HMOs to new homes bought off-plan and purpose-built rental developments. Each offers a different balance of purchase price, rental return, management and risk.
Sources: HM Land Registry – house price data , Office for National Statistics – private rental market data, Rightmove – rental and property market data, Zoopla – property market data, Manchester City Council – housing, planning and regeneration data, Greater Manchester Combined Authority – economic, population and development data, Relevant local/regional sources used for individual figures
Buy-to-let apartments can be found throughout Greater Manchester, but there is a particularly high concentration in the centre of the city, where they account for around 93% of residential sales over the past year, with 1,290 sold compared with fewer than 100 houses.
In Manchester Central, 61% of households are privately rented, and the average renter is just 26, helping to support demand from young professionals, graduates and students.
New housing in the city centre is heavily weighted towards apartments too. Around 85% of the 3,419 homes completed in 2024/25 were flats, and they are expected to account for an even greater proportion of new housing over the longer term.
Apartments can provide a relatively accessible entry point, with the average price of a one-bedroom property around £167,000, compared with around £250,000 for a terraced house and £472,000 for a detached home.
Gross rental yields for flats are among the highest for conventional buy-to-let properties, at around 7.0%, although service charges and other leasehold costs reduce the income retained.
View buy-to-let properties for sale in Manchester
Off-plan property is bought before construction is completed, and sometimes before building work has begun. Buyers reserve a property at the development stage and complete the purchase once it is finished.
The main attraction is the opportunity to buy early, when developers may offer lower launch prices, discounts or other incentives. There is usually a wider choice of properties at this stage too, and if prices rise during construction, the property may be worth more by the time it is completed.
Because of the scale of its new residential development, Manchester offers plenty of opportunity to buy off-plan. Around 3,400 homes were completed in 2024/25, with thousands more planned as major regeneration and development schemes expand the city’s housing stock.
BuyAssociation’s relationships with developers can provide access to properties at an early stage, including off-market opportunities and developments before their wider release.
Buying before completion does carry additional risks. There is no rental income during construction, and property values, achievable rents and mortgage rates can change before the property is finished. The developer’s track record, location, payment schedule and expected completion date therefore need to be carefully considered.
Build-to-rent (BTR) developments are designed exclusively for the rental market. They often include shared facilities such as gyms, co-working areas and residents’ lounges, as well as services such as a concierge.
These facilities are designed to appeal to tenants and encourage longer tenancies, which helps reduce turnover and void periods.
Manchester has one of the UK’s most established BTR markets. More than 19,000 homes have been delivered across Greater Manchester, including around 9,000 in Manchester and 8,000 in Salford. The sector has expanded beyond premium city-centre apartments, with developments now serving a much broader rental market.
BTR can be a more hands-off investment, as developments are usually run by professional management companies. The trade-off is cost: the management and shared facilities need to
HMOs have become an increasingly popular form of property investment because letting rooms individually can produce significantly higher rental yields than a conventional buy-to-let, with gross yields of 10% or more possible.
A house in multiple occupation (HMO) is a property rented by at least three people from more than one household who share facilities such as a kitchen or bathroom. There are two main markets: student HMOs, typically rented by groups of students, and professional HMOs, where rooms are generally rented individually to working tenants.
Manchester has a large market for both. Student HMOs are concentrated in south Manchester, particularly Fallowfield and Withington and along the Oxford Road and Wilmslow Road corridor. The rest of the HMO market is more widely spread, serving young professionals and other sharers looking for affordable accommodation close to employment and good transport links.
The attraction is the higher income that can be generated from letting several rooms separately. It also means that if one room is empty, the property can still generate income from the remaining tenants.
Those higher returns, however, come with greater management and regulation. HMOs can be subject to additional licensing, planning, fire safety and property standards requirements, making them more complex to operate than a conventional buy-to-let.
								Array
(
    [ID] => 6108014
    [id] => 6108014
    [title] => Shot1 nw
    [filename] => Shot1-nw-scaled.jpg
    [filesize] => 1771498
    [url] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-scaled.jpg
    [link] => https://www.buyassociationgroup.com/en-gb/piccadilly-wharf-city-am/shot1-nw/
    [alt] =>
    [author] => 627
    [description] =>
    [caption] =>
    [name] => shot1-nw
    [status] => inherit
    [uploaded_to] => 6108008
    [date] => 2026-08-11 13:43:07
    [modified] => 2026-08-11 13:43:07
    [menu_order] => 0
    [mime_type] => image/jpeg
    [type] => image
    [subtype] => jpeg
    [icon] => https://www.buyassociationgroup.com/en-gb/wp-includes/images/media/default.png
    [width] => 2560
    [height] => 2560
    [sizes] => Array
        (
            [thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-150x150.jpg
            [thumbnail-width] => 150
            [thumbnail-height] => 150
            [medium] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-400x400.jpg
            [medium-width] => 400
            [medium-height] => 400
            [medium_large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-768x768.jpg
            [medium_large-width] => 768
            [medium_large-height] => 768
            [large] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-1024x1024.jpg
            [large-width] => 1024
            [large-height] => 1024
            [1536x1536] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-1536x1536.jpg
            [1536x1536-width] => 1536
            [1536x1536-height] => 1536
            [2048x2048] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-2048x2048.jpg
            [2048x2048-width] => 2048
            [2048x2048-height] => 2048
            [post-thumbnail] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-125x125.jpg
            [post-thumbnail-width] => 125
            [post-thumbnail-height] => 125
            [landscape_600x400] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-600x400.jpg
            [landscape_600x400-width] => 600
            [landscape_600x400-height] => 400
            [landscape_500x300] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-500x300.jpg
            [landscape_500x300-width] => 500
            [landscape_500x300-height] => 300
            [landscape_750x350] => https://www.buyassociationgroup.com/en-gb/wp-content/uploads/sites/2/2026/08/Shot1-nw-750x350.jpg
            [landscape_750x350-width] => 750
            [landscape_750x350-height] => 350
        )

)
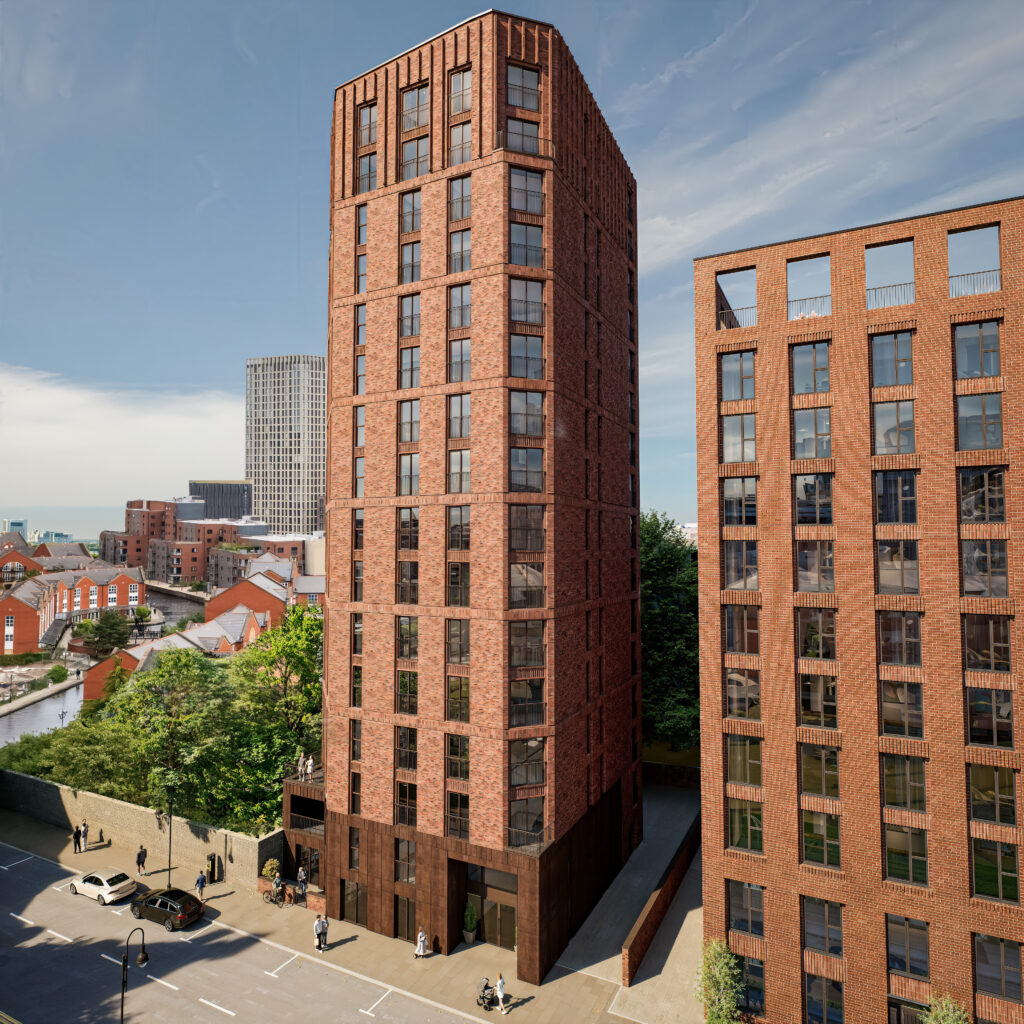
Manchester currently has an average gross rental yield of 6.5%, compared with 5.9% for England and just 5.0% for London.
| Manchester | England | London | |
|---|---|---|---|
| Average property price | £251,250 | £293,262 | £553,870 |
| Average monthly rent | £1,358 | £1,446 | £2,302 |
| Gross rental yield | 6.5% | 5.9% | 5.0% |
| 5-year rental growth | 44.3% | 33.8% | 34.4% |
| 5-year property price growth | 18.8% | 10.2% | 2.9% |
Sources: HM Land Registry and ONS, June 2026.
Manchester has outperformed both England and London on almost every measure. Its average gross rental yield is higher, and both rents and property prices have grown more strongly over the past five years. At the same time, the average purchase price remains considerably lower than both England and London.
There are significant differences within Manchester itself, with flats and terraced houses currently producing the strongest average yields among conventional property types.
| Property type | Average price | Average monthly rent | Gross rental yield |
|---|---|---|---|
| Flat/maisonette | £195,385 | £1,136 | 7.0% |
| Terraced | £252,957 | £1,390 | 6.6% |
| Semi-detached | £327,725 | £1,479 | 5.4% |
| Detached | £478,105 | £1,858 | 4.7% |
Sources: HM Land Registry and ONS, June 2026.
Flats have the highest average conventional yield in Manchester at 7.0%, followed closely by terraced properties at 6.6%. Larger houses command higher rents, but their higher purchase prices result in lower average yields.
Location makes a substantial difference too, as the figures for some of Manchester and Greater Manchester’s key investment areas show.
| Area | Postcode | Average sold price | Average asking rent | Gross rental yield | 5-year property price growth |
|---|---|---|---|---|---|
| Manchester city centre | M1 | £236,462 | £1,476 | 6.7% | -14% |
| Ancoats/New Islington | M4 | £246,203 | £1,384 | 6.8% | -8% |
| Salford Quays | M50 | £193,202 | £1,207 | 6.7% | -3% |
| Stockport town centre | SK1 | £211,597 | £955 | 5.5% | +38% |
Sources: Zoopla, August 2026 (average sold prices over the last 12 months); PropertyData, August 2026 (postcode district asking rents, gross rental yields and five-year property price growth).
Note: PropertyData calculates gross rental yields using average asking rents and average asking prices. As the average sold prices shown above are from Zoopla, the yields cannot be calculated directly from the prices and rents shown.
Central Manchester currently produces some of the strongest yields, with M1, M4 and M50 all around 6.7–6.8%. Stockport’s SK1 offers a lower yield of 5.5%, but has recorded much stronger property price growth over the past five years.
The headline yield, though, is only one part of the picture. A higher yield can provide stronger rental income relative to the purchase price, whereas capital growth affects the longer-term value of the investment. The two do not necessarily move together.
Gross yields also don’t account for costs such as management fees, service charges, maintenance, mortgage payments and periods without a tenant, all of which affect the return from an individual property.
Note: These figures are market benchmarks rather than guaranteed returns. Actual rents, purchase prices and yields will vary between individual properties and locations, including from street to street within the same postcode.
Speak to a property investment consultant about current Manchester yields and opportunities.
STAY AHEAD OF THE MARKET
We send limited and targeted emails on new launches and exclusive deals which best fit your areas. We are trusted by over 30,000 active buyers as their source for new stock.
Manchester’s property market is being supported by rapid population growth, a large student and graduate population, expanding employment and billions of pounds of investment in transport, regeneration and new development.
These factors are closely connected. Universities bring young people into the city, growing businesses create jobs that encourage them to stay, and major infrastructure and regeneration projects are opening up new places to live and work.
Manchester’s population has grown rapidly over the past two decades, increasing by around 42% between 2005 and 2025 to an estimated 645,097.
It is also a particularly young city. The 2021 Census found that Manchester had a median age of just 31, with 20 to 24-year-olds its largest five-year age group at almost 62,000 people. A further 52,600 residents were aged between 25 and 29.
This concentration of younger residents helps support a large rental market. Manchester has around 100,000 privately rented homes, accounting for approximately 40% of its housing stock.
Manchester’s universities are an important part of that demographic picture. More than 125,000 students study in Greater Manchester, creating substantial demand for accommodation during their studies, but their influence on the property market extends well beyond the student sector.
Around 40% then remain in Greater Manchester after graduating, strengthening the local workforce and helping to replenish the city’s population of young professionals. Retention is particularly strong in sectors such as health innovation and life sciences.
That ability to retain graduates provides employers with a steady supply of skilled workers and helps support Manchester’s economic growth.
Alongside its population, Manchester’s employment base has expanded rapidly. Jobs in Manchester and the wider city region have increased by 19.7% over the past decade, compared with 13.9% nationally, and Manchester’s employment rate is now above 75%.
The number of businesses in the city has grown by 30% since 2015, with around 900 added in 2024/25 alone. Manchester now has around 244,000 knowledge-intensive business-services jobs, which is second only to London among major UK cities.
Growth is spread between a wide range of sectors, including digital technology and AI, fintech, financial and professional services, life sciences, advanced manufacturing, research and the creative industries.
And there is a substantial pipeline of new employment and investment still to come.
The Manchester Digital Campus in Ancoats is being developed as a major government technology hub, bringing together around 8,800 people from multiple government departments in 900,000 sq ft of workspace. Groundworks began in June 2026, and construction itself is expected to support around 4,900 jobs. The government says the project should help galvanise Manchester’s wider digital sector rather than operate simply as a standalone office development.
The new No. 10 North operation will add another dimension. Prime Minister Andy Burnham has based the new economic growth hub in Manchester and is transferring responsibility for driving the government’s growth agenda to it. As well as bringing government jobs to Manchester, it will put the city closer to national economic decision-making and will attract businesses that work closely with government.
Manchester is also in the middle of a major expansion of its transport infrastructure.
Greater Manchester has secured £2.5 billion of Transport for City Regions funding, supporting plans including an extension of Metrolink to Stockport, new tram stops, further expansion of the Bee Network and the introduction of local rail services into the integrated transport system.
The longer-term plans are considerably larger. Northern Powerhouse Rail includes a new Liverpool-Manchester route through Warrington and Manchester Airport, alongside improved east-west connections towards Leeds, Bradford and Sheffield.
Manchester Piccadilly will become a major hub for the expanded network, strengthening rail connections between Manchester, Liverpool and other major cities in the North.
In addition, Burnham has recently pledged to revive the high-speed connection between Birmingham and Manchester lost when the northern leg of HS2 was cancelled, although the precise form and delivery timetable of the new railway have yet to be determined.
For Manchester’s property market, better local and intercity transport can increase the number of places within a practical commute of major employment centres and help support the development of new residential districts.
Transport investment forms part of a much bigger development story, with entire new neighbourhoods being created or planned around Manchester.
Victoria North is one of the largest, with the £4bn regeneration programme set to deliver around 15,000 homes across seven neighbourhoods north of the city centre, eventually accommodating approximately 40,000 residents.
Development is already well underway, with the final homes at the 634-home Victoria Riverside development completed in August 2026 and St Catherine’s Wood opening the previous month.
Piccadilly is another huge long-term opportunity. Plans for the wider station district envisage around 13,000 homes, up to 40,000 jobs and 820,000 sq m of commercial development.
There is significant investment outside the immediate city centre too. North Manchester has a £6 billion, 15 to 20-year investment strategy, including Victoria North and the redevelopment of North Manchester General Hospital.
Old Trafford is potentially another development on a similar scale. The new 370-acre Mayoral Development Corporation has ambitions for 15,000 homes and 48,000 local jobs, alongside Manchester United’s plans for a new 100,000-seat stadium. The wider regeneration programme has been estimated to have the potential to contribute more than £7 billion a year to the UK economy.
Burnham is also backing potential UK bids for the 2040 Olympic and Paralympic Games and the 2042 FIFA World Cup. Whether or not the bids are successful, they will give Manchester global exposure.
Manchester’s growth means it requires substantially more housing, and it is building at a significant rate, with a record 4,766 new homes completed during 2025/26.
And, moving forward, Manchester City Council has a target of delivering 36,000 homes between 2022 and 2032, including at least 10,000 social, council or genuinely affordable properties.
Rising rents, however, are an indication that supply is not keeping up with demand.
Manchester has delivered strong rental and property price growth in recent years, but past performance does not guarantee future returns.
Property prices can rise or fall in response to changes in the economy, demand, interest rates and local market conditions.
Rental yields vary significantly depending on the location, property type, purchase price and rent achieved.
Interest rates and mortgage costs can change during the lifetime of an investment and need to be factored into expected returns. Buy-to-let mortgages can also have different lending criteria and costs from residential mortgages.
Apartments normally have service charges covering the management and maintenance of the building and communal areas. These costs should be factored into calculations when assessing potential returns.
Buyers of leasehold properties should check the terms and remaining length of the lease, along with any restrictions or other ongoing charges, before purchasing.
Buying before completion can provide access to properties at an earlier stage of a development, but construction can be delayed, and property values and market conditions can change before completion.
Buyers should also check the developer’s track record and ensure they understand the terms of the purchase.
Landlords should allow for periods when a property may be empty between tenants or during maintenance work, reducing the rental income received.
Letting and property management fees, along with maintenance and insurance costs, will reduce the net return from a property.
Property taxation and landlord regulations can change over the lifetime of an investment, potentially affecting costs and returns, so it’s important landlords stay up to date.
Useful guides: Find out more about buy-to-let property investment, mortgages, off-plan investment, and property tax and accounting in our specialist guides.
For those looking to invest in Manchester property, the city offers high rental demand, competitive yields and long-term capital growth. Average property prices have risen by 73.4% over the past decade, rents by 70.6%, and the city’s current average gross rental yield is 6.5%. Its growing population, employment and extensive regeneration help underpin demand.
Although the wider property market is challenging in 2026, Manchester is outperforming much of the country. Property prices were 2.9% higher year-on-year in June, compared with 1.8% across the UK, and rents were up 3.5%. The longer-term outlook remains positive too, with large-scale regeneration and infrastructure projects in the pipeline and a new Northern political hub.
The average gross rental yield in England is currently 5.9%, with anything between 5% and 8% considered good. In Manchester, the average is 6.5%, rising to 7.0% for flats and maisonettes and 6.6% for terraced properties. As these figures are averages, it is possible to achieve more, and HMOs can produce yields of over 10%.
Buy-to-let in Manchester city centre has strong demand from young professionals, graduates and students attracted by its concentration of jobs, universities, transport and amenities. M1 currently has an average asking rent of £1,476 a month and a gross rental yield of 6.7%, with regeneration and employment growth supporting longer-term capital growth. The market is dominated by apartments, so service charges and other leasehold costs need to be considered alongside the headline yield.
Manchester property prices were 2.9% higher year-on-year in June 2026, compared with growth of 1.8% across the UK and a 2.5% fall in London. Longer term, average Manchester prices have risen 18.8% over five years and 73.4% over ten years. However, performance varies considerably by location, with some central Manchester postcodes recording falls over the past five years.
The best area will depend on your priorities, including whether you are looking for higher rental yields or longer-term capital growth, as well as how much management you want to take on. Manchester city centre and areas such as Ancoats and Salford Quays are popular for apartments with strong professional rental demand, while locations further from the centre can offer a wider choice of property types and different combinations of purchase price, rental yield and capital growth. HMOs, particularly in student areas, can offer yields of 10% or more, but typically require more active management..
Manchester remains considerably cheaper than London and slightly cheaper than England as a whole. The average Manchester property price was £251,250 in June 2026, around 14% below the England average of £293,262 and 55% below London’s £553,870.
Manchester has a substantial pipeline of investment that could support further growth. Major projects include Victoria North, Manchester Digital Campus and No. 10 North, redevelopment around Piccadilly and Old Trafford, and major transport investment through Northern Powerhouse Rail. Manchester is also targeting 36,000 new homes between 2022 and 2032 to accommodate its growing population. These developments provide a strong backdrop, although future property prices and rental returns cannot be guaranteed.
BuyAssociation assesses a range of factors when sourcing investment property in Manchester, from the strength of the location to the individual development and property.
The process starts with the location, looking at property prices, rents and yields, tenant demand, economic and population growth, and planned regeneration and infrastructure.
This helps identify not only established investment locations, but areas where new transport links, regeneration or economic growth could create opportunities in the future.
BuyAssociation then assesses the development and the individual properties available within it. Purchase price, achievable rent, potential rental yield and local demand are considered alongside the characteristics of the property and the longer-term prospects for the surrounding area.
Who is behind the development is also a key consideration. BuyAssociation has built long-standing relationships with some of the UK’s most reputable developers. These relationships can provide access to projects at an early stage, including off-market opportunities before they become available to the wider market.
Working with a large international investor base also gives BuyAssociation group buying power, which can provide access to discounted properties and particular units within developments where available.
Once a suitable property has been identified, BuyAssociation’s consultants can support buyers through the purchase process and connect them with independent specialists where required, including mortgage advice, lettings management and furnishing services.
Access advice and unique property investment opportunities directly from leading developers throughout the UK
Please read
I declare that I am a self-certified sophisticated investor for the purposes of the restriction on promotion of non-mainstream pooled investments. I understand that this means:
I am a self-certified sophisticated investor because at least one of the following applies:
I accept that the investments to which the promotions will relate may expose me to a significant risk of losing all of the money or other property invested. I am aware that it is open to me seek advice from someone who specialises in advising on non-mainstream pooled investments.
Please read
I make this statement so that I can receive promotional communications which are exempt from the restriction on promotion of non-mainstream pooled investments. The exemption relates to certified high net worth investors and I declare that I qualify as such because at least one of the following applies to me:
I accept that the investments to which the promotions will relate may expose me to a significant risk of losing all of the money or other property invested. I am aware that it is open to me to seek advice from an authorised person who specialises in advising on non-mainstream pooled investments.
STAY AHEAD OF THE MARKET
We send limited and targeted emails on new launches and exclusive deals which best fit your areas. We are trusted by over 30,000 active buyers as their source for new stock.
FIRST FOR NEWS AND KNOWLEDGE.
Established since 2005 we are a leading voice of authority and commentary on the UK property market. Our news is trusted by Apple News & Google News.
Speak to our UK property experts today:
Open from 9am-6pm GMT
Open from 9am-6pm HKT